When Celsius collapsed, its Earn clients realized that the crypto of their accounts belonged to the chapter property, to not them. Sen. Cynthia Lummis solid the CLARITY Act as a repair on July 20, boiling its promise all the way down to 4 phrases.
“Your crypto stays yours.”
Her X publish, which had drawn a whole lot of consideration, mentioned the CLARITY Act would change the end result she related to the failures of Celsius and Voyager.
Celsius might be one of the best authorized instance as a result of a federal courtroom dominated straight on possession of its Earn balances.
The Might 12 Senate Banking supervisor’s substitute helps the course of Lummis’s declare whereas attaching a number of situations. Part 701 would put qualifying ancillary property and digital commodities into federal customer-property guidelines when they’re “held for purchasers” in specified Chapter 7 liquidations.
The safety could not apply if the asset, account phrases, or chapter course of falls outdoors the invoice’s boundaries. A qualifying token held in custody for a buyer matches the language extra naturally than a steadiness created after the shopper lends an asset or transfers title to the platform. The textual content leaves that lending boundary open for last laws and future courts.
The place Part 701 attracts the road
Part 701 will rewrite the chapter guidelines for liquidating failed stockbrokers. It provides ancillary property and digital commodities to related definitions of consumers, buyer claims, and buyer property. It additionally directs liquidations underneath subchapters III or IV of Chapter 7 to deal with these property as buyer property when held for purchasers and to distribute them underneath Title 11.
The official section-by-section abstract describes Part 701 as defining ancillary property and digital commodities as buyer property underneath Chapter 7. The operative textual content provides the boundaries behind that abstract.
The invoice’s safety additionally depends upon how the asset is classed. Part 701 names ancillary property and digital commodities. Securities and money held by a broker-dealer stay ruled by the Securities Investor Safety Act. Financial institution deposits and commodity contracts stay underneath their different relevant legal guidelines.
Cost stablecoins seem individually in Part 804, which might require broker-dealer disclosures concerning the insolvency therapy of fee stablecoins, digital commodities, and a safety involving a unit of a digital commodity. That construction leaves Part 701 unable, by itself, to help one rule for each stablecoin steadiness.
Account phrases matter simply as a lot. “Held for purchasers” factors to custody, the place the shopper retains possession. Lending and yield merchandise can work in a different way. If the contract transfers possession to the platform, the shopper could also be left with solely a declare for reimbursement.
Celsius confirmed how pricey that distinction could be. In a Jan. 4, 2023 order, the U.S. Chapter Courtroom for the Southern District of New York mentioned Celsius had roughly 600,000 Earn accounts holding about $4.2 billion in crypto as of July 10, 2022.
For the courtroom, possession got here all the way down to the contract. Celsius’s phrases gave the corporate “all proper and title” to crypto deposited in Earn. The courtroom held that the crypto remaining in these accounts belonged to the chapter estates. Earn customers had been usually unsecured collectors whose restoration relied on the chapter distribution. Its app would present the identical acquainted steadiness even after a buyer had traded possession of the crypto for an IOU from Celsius.
Celsius concerned title-transferring Earn phrases, whereas Part 701 addresses qualifying buyer property in specified Chapter 7 proceedings. The case subsequently illustrates the possession query at stake with out establishing how Part 701 would apply to an identical yield product.
The proposed classes produce totally different threat profiles:
| Account relationship | Part 701 relevance | Major restrict |
|---|---|---|
| Qualifying middleman custody | The clearest match when an ancillary asset or digital commodity is held for the shopper in a coated Chapter 7 liquidation. | The asset, middleman and liquidation should fall throughout the provision’s definitions and scope. |
| Lending, Earn or yield account | Protection stays unresolved when the settlement transfers title or makes the platform a borrower. | Contract language can flip the shopper’s steadiness into an unsecured declare, as Celsius demonstrated. |
| Independently managed self-custody | Part 605 governs this relationship individually by defending lawful self-custody for an outlined coated consumer. | The availability preserves illicit-finance, anti-money-laundering, terrorism-financing and sanctions enforcement. |
| Dealer-dealer securities or money, financial institution deposits and commodity contracts | Part 701 assigns these classes to different authorized regimes. | Safety follows SIPA, banking regulation, commodities regulation or one other relevant framework. |
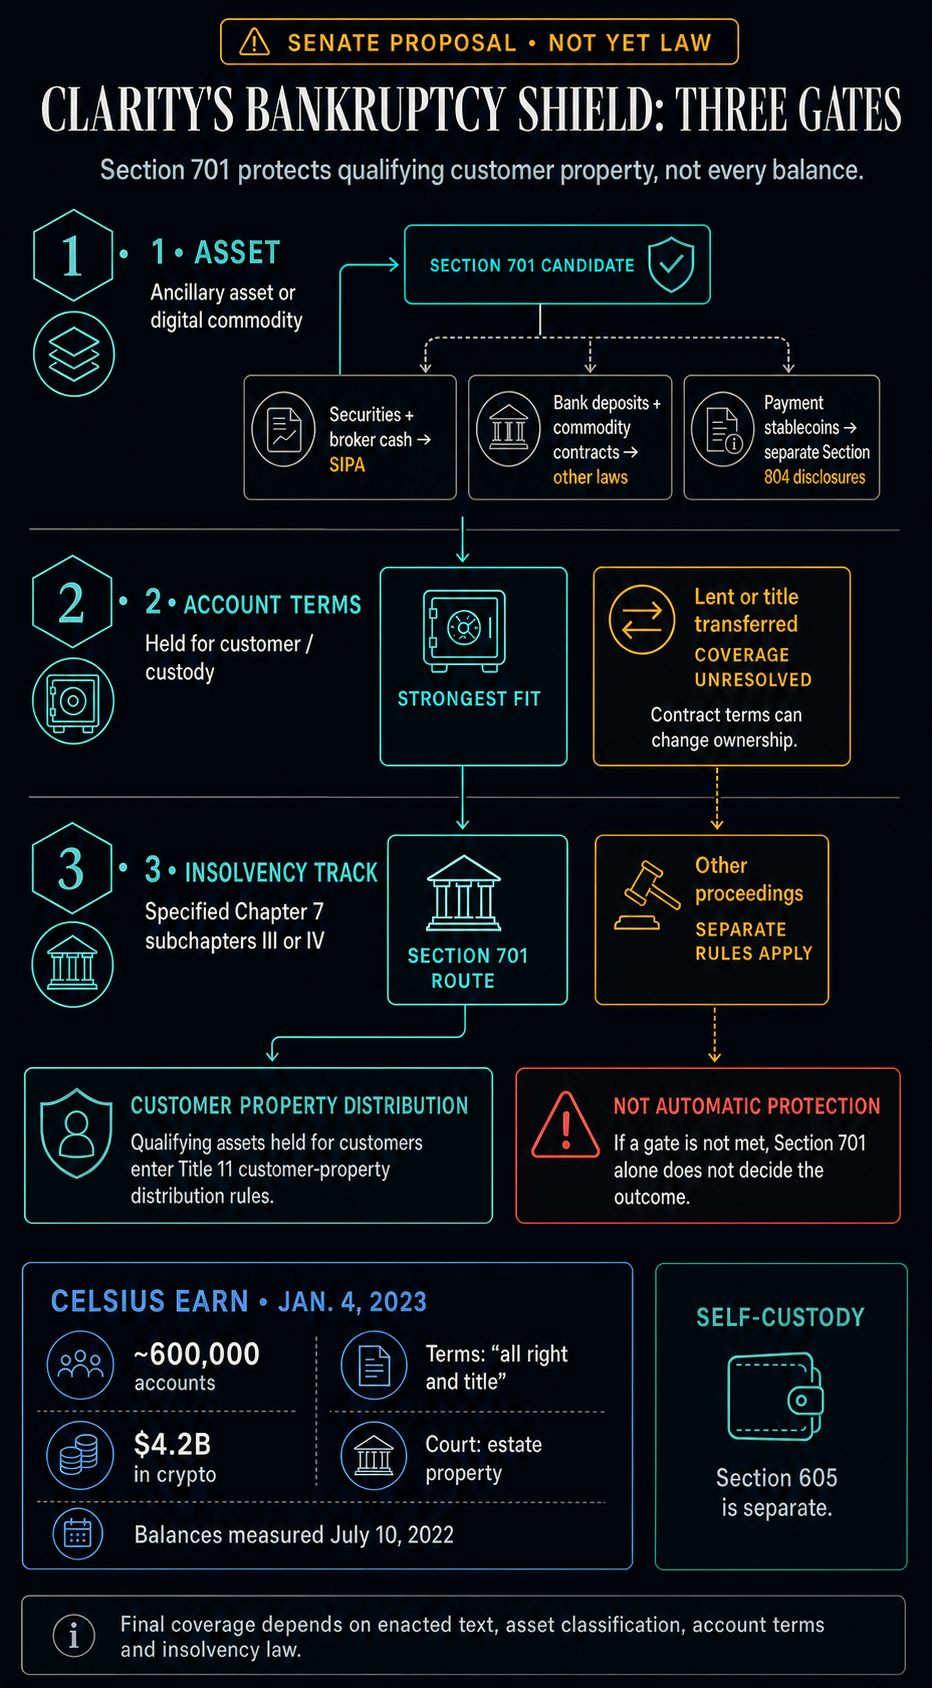
If a platform is just holding qualifying crypto for a buyer, Part 701 will place it within the customer-property pool throughout chapter. Loans are murkier. As soon as a contract arms possession to the platform, a choose could must determine whether or not the shopper nonetheless owns crypto or merely holds an IOU.
Self-custody sits outdoors that middleman relationship. Part 605 individually protects lawful self-custody by outlined coated customers by way of self-hosted wallets whereas retaining present enforcement authorities. Its presence reinforces the invoice’s distinction between property managed by their proprietor and property positioned with a monetary middleman.
The safety continues to be a proposal
The Senate Banking Committee superior H.R. 3633 by a 15-9 vote on Might 14. Committee passage left Senate flooring approval and subsequent legislative steps excellent.
As CryptoSlate reported on July 14, the broader Senate bundle stays unfinished, and no flooring vote has been scheduled.
The client-property provision is only one a part of a broader market-structure effort whose Might 12 textual content additionally addresses token classification, stablecoin rewards, decentralized finance and banking powers.
The following legislative take a look at is whether or not Part 701 retains its present wording because the bundle strikes ahead. The pragmatic take a look at would observe in platform contracts: whether or not exchanges describe balances as custody, lending or one other relationship, and whether or not these phrases say the platform holds the asset for the shopper or receives possession of it.
Lummis’s promise captures the supply’s objective and compresses its situations. Qualifying ancillary property and digital commodities held as buyer property would enter the customer-property distribution guidelines. A steadiness created by a title-transferring mortgage would nonetheless require the asset classification, contract, and insolvency regime to align earlier than “your crypto stays yours” turns into the authorized consequence.