If each month ends with the identical quiet dread…
Do I’ve sufficient to cowl payroll?
What occurred to the cash from that huge bill from six weeks in the past?
…You’re not struggling since you’re unhealthy at enterprise; you’re struggling as a result of nobody ever taught you find out how to handle and forecast your money move.
A lot of the recommendation out there may be both too primary or written for seasoned finance execs. This information is for the individual truly working the numbers, not a finance textbook.
The Fundamentals of Money Movement Forecasting and Administration
Money move is just the motion of cash into and out of your enterprise.
- Cash in: Shopper funds, gross sales, deposits.
- Cash out: Hire, payroll, software program subscriptions, provides, taxes.
Money move administration means monitoring, analyzing, and planning round that motion so that you’re by no means caught off guard.
Money move forecasting takes it a step additional; it’s the apply of projecting what your inflows and outflows will seem like over an outlined future interval, normally the subsequent 30, 60, or 90 days.
Similar to forecasting the climate, it will not be 100% proper the entire time, however it’s best to get caught out within the rain much less.
Right here’s what a easy money move forecast would possibly seem like for a boutique consulting agency:
| Week | Anticipated Revenue | Anticipated Bills | Projected Steadiness |
| 1 | $4,200 (Shopper A bill due) | $2,800 (payroll, software program) | +$1,400 |
| 2 | $0 | $1,200 (contractor) | -$1,200 |
| 3 | $6,500 (Shopper B fee) | $3,100 (hire, utilities) | +$3,400 |
| 4 | $1,000 (retainer) | $900 (provides) | +$100 |
Even this primary snapshot tells you one thing important: Week 2 is lean. You’ll be able to plan for it — defer a non-urgent buy, ensure that an bill goes out every week earlier, or preserve a buffer prepared.
Understanding Money Movement vs. Revenue
Revenue is finally an accounting idea. It’s what stays after you subtract bills from income.
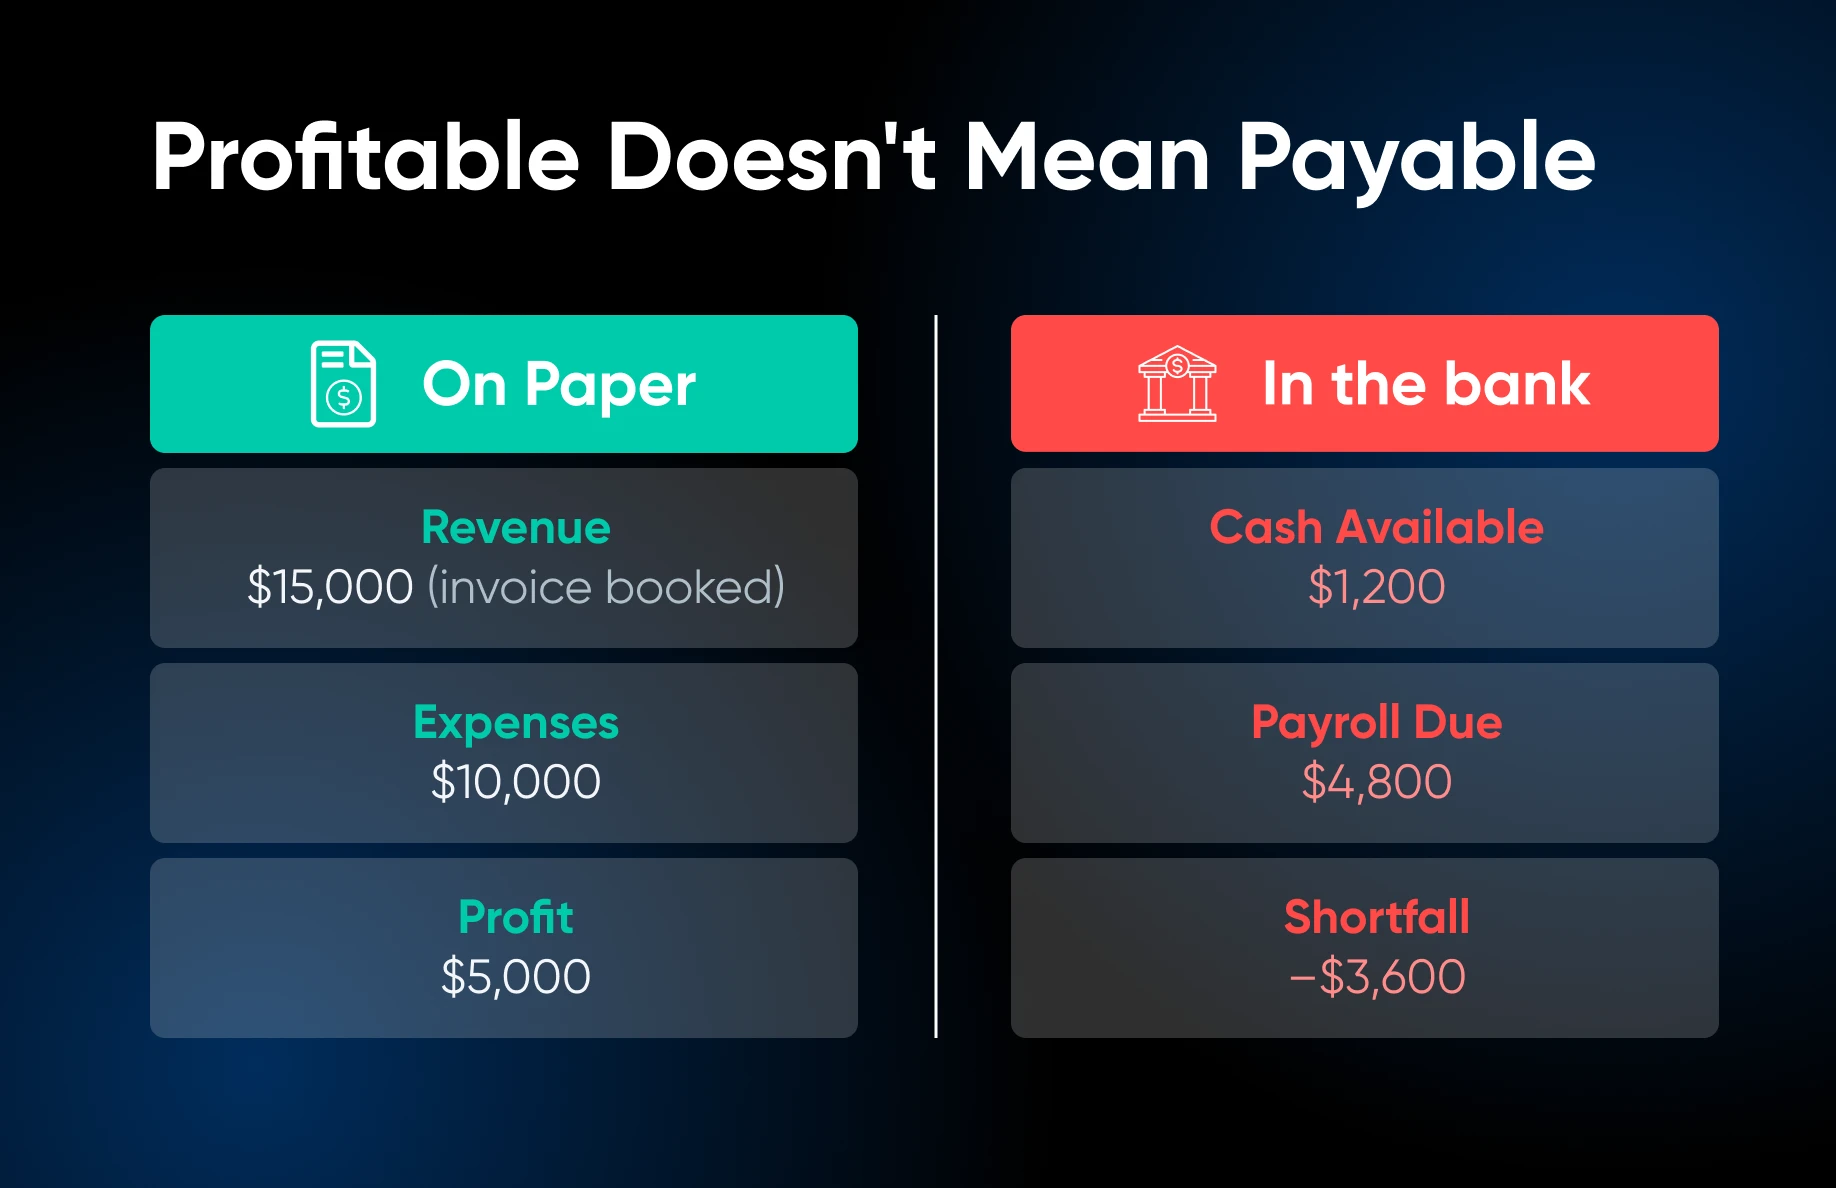
Money move is what’s truly in your checking account proper now. It’s the quantity that determines whether or not you can also make payroll — not simply whether or not you’re technically worthwhile.
You might be worthwhile on paper and nonetheless be unable to make payroll resulting from lack of money.
If a consumer owes you $15,000, that counts as income. You’re trying nice! However till that verify clears, it’s not money you should use. That’s not so nice when payroll is developing and your checking account is strapped.
This mismatch is strictly why so many in any other case wholesome companies run into hassle. You’ll be able to see how staying solvent has a lot to do with managing and forecasting the precise move of money, not simply totals.
The perfect forecasting system is one you’ll keep on with. Right here’s find out how to construct one thing sensible.
Step 1: Set Your Baseline
Pull the final three months of financial institution statements and categorize your bills:
- Fastened bills are predictable; they embrace hire, subscriptions, mortgage funds, and so forth.
- Variable bills are tougher to anticipate; they sometimes confer with provides, contractors, and promoting.
These develop into your expense estimates going ahead.
Step 2: Checklist Anticipated Money In
Undergo your open invoices and lively consumer contracts. Be aware due dates and, be sincere right here, how reliably every consumer pays.
If Shopper A routinely pays 30 days late, plan for that…regardless that it’s a bummer.
Step 3: Assemble a 90-Day Forecast
That is actually the center of successfully managing cashflow.
The objective is to get visibility into a number of months of projected cash in, cash out, and your working stability. You’re not going to have the ability to predict every little thing, however to proceed the climate analogy,try to be higher ready for any storms.
Choice A: Google Sheets (Free, however Closely Guide)
Create a row for every of the subsequent three months, or get extra granular and checklist out 12 weeks in case your money move is extra erratic.
Listed here are the columns you’re filling out for every month/week:
- Opening Steadiness: Your precise financial institution stability at the moment goes in row 1. Each row after that pulls from the earlier row’s Closing Steadiness robotically. Right here’s the method: =earlier row’s Closing Steadiness.
- Anticipated Revenue: Enter each fee you realistically count on to obtain in that interval. Embody confirmed consumer invoices, recurring retainer funds, and another predictable income. Don’t embrace “maybes,” solely cash you’ve gotten affordable confidence in. If a consumer persistently pays two weeks late, enter it two weeks later than the due date.
- Anticipated Bills: Checklist each outgoing fee: hire, payroll, contractor charges, software program subscriptions, mortgage funds, estimated taxes, and any recognized one-time prices. Fastened bills are straightforward, they’re the identical each month. For variable bills, use your common from the final three months because the estimate.
- Closing Steadiness: That is simply [Opening Balance + Expected Income – Expected Expenses.] In Sheets, that method takes 5 seconds to put in writing and auto-calculates the remaining.
💡Professional tip: Shade code your closing stability column; inexperienced if it’s comfortably above your reserve threshold, yellow if it’s getting shut, pink if it dips beneath. You now have a visible early-warning system.
Choice B: Use Accounting Software program (Comes With Charges, however Extra Options)
In case you’re already utilizing QuickBooks On-line, FreshBooks, or Wave, it’s possible you’ll not want a separate spreadsheet in any respect.
For instance, most QuickBooks On-line plans have a built-in Money Movement Planner that robotically pulls in your scheduled invoices and recurring payments and tasks your stability ahead 90 days.
FreshBooks surfaces money move indicators on its dashboard — excellent invoices, revenue, and cash in/out — and has a devoted Money Movement report beneath its Studies tab. Wave requires a bit extra handbook setup however its experiences part will get you there.
The benefit of those instruments is that they sync along with your checking account and invoicing, so your forecast updates robotically as invoices receives a commission or new bills are available in.
The tradeoff is much less flexibility than a customized spreadsheet. However for many small enterprise homeowners, that automation is price it.
Step 4: Replace Your Rolling Forecast
“Rolling” means you’re all the time trying 90 days forward, not at a set window.
Each Friday, or each Monday morning — decide one and follow it, spend quarter-hour doing the next:
- Transfer your opening stability to your precise present financial institution stability.
- Mark any anticipated funds that got here in or didn’t.
- Add the subsequent week or month to the tip so that you’re all the time trying 90 days out.
- Be aware something that modified, like a brand new contract signed, an expense that got here in increased than anticipated, or a consumer who requested for prolonged phrases.
Step 5: Set a Minimal Money Reserve Threshold
Similar to you’ve gotten a security web on your private funds (proper?!), you want one for your enterprise, too.
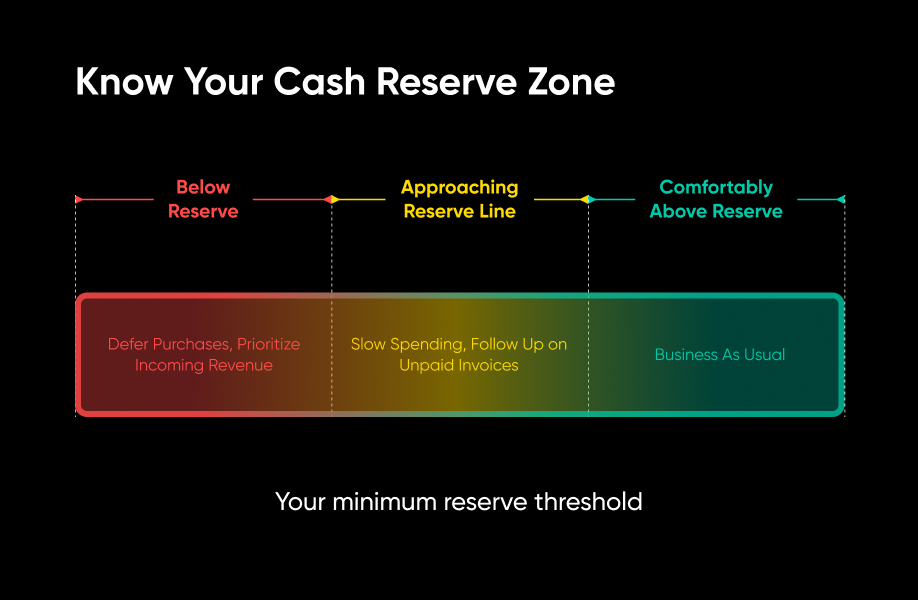
Set a minimal money reserve quantity that you simply by no means need your enterprise checking account to fall beneath. For a lot of small companies, this can be one to 3 months of working bills, relying on how predictable income is.
Three months appears to be the max for the common small enterprise, as 70% report retaining lower than 4 months of money available to cowl working bills.
Deal with this reserve as untouchable apart from true emergencies.
Having a transparent threshold provides you an early warning system earlier than money move issues develop into critical. In case your stability begins getting too near that quantity, it’s an indication to gradual spending, observe up on unpaid invoices, delay nonessential purchases, or deal with bringing in income quicker.
Step 6: Automate The place You Can
Arrange recurring invoices for retainer purchasers, computerized fee reminders, and automatic expense categorization.
Each handbook step you get rid of is one fewer factor that falls via the cracks, and getting invoices out quicker means getting paid quicker. Automated fee reminders alone can shorten the time between sending an bill and getting paid — which suggests money in your account sooner, not only a job off your checklist.
What Makes Forecasting and Administration Vital, Particularly for You
With bills and payroll prices rising, at the moment the revenue-to-expenses ratio for many small companies is nearly 1:1.
Margins?
Rattling close to invisible.
So it’s no shock that 71% of companies say they’re involved they gained’t have sufficient money move to cowl their bills.
It’s excessive time small companies construct up their money move confidence.
In our opinion, it’s probably the greatest methods to cut back stress and unlock progress. When you realize precisely what’s coming in and going out, you can also make huge selections round hiring, shopping for tools, advertising spend, and so forth with out the anxiousness that comes from flying blind.
Regardless of the doom and gloom the stats might counsel, hopes are nonetheless excessive. Greater than 90% of small biz homeowners count on reasonable and even important progress!
The optimism is there.
The massive hole?
Infrastructure; that’s, the techniques and habits that flip ambition into actual income.
A high quality (in line with 60% of customers) web site is a part of that infrastructure.
A well-built web site is likely one of the lowest-friction methods to herald extra purchasers. Extra purchasers imply extra cash to forecast.
How’s the Forecast Trying?
Similar to the climate, money move will get an entire lot much less unpredictable the second you possibly can see what’s coming.
That’s the entire level of monetary forecasting. It’s not an ideal prediction, nevertheless it offers sufficient visibility to identify the lean weeks early and plan round them.
The trail is simple. First, set your baseline from the final three months, checklist your anticipated revenue truthfully, and construct a 90-day forecast in no matter software you’ll truly keep on with (a free, versatile spreadsheet or accounting software program that updates itself are each nice choices!).
From there, preserve the monetary administration rolling with a 15-minute weekly check-in, set a minimal money reserve you deal with as untouchable, and automate the repetitive items so fewer issues slip via the cracks.
Most small enterprise homeowners see progress on the horizon. A monetary forecasting and administration system helps you flip that hope into an actionable plan.

Cease Chasing Invoices. Automate Your Enterprise Funds.
A free playbook for small companies: automate expense monitoring, funds, money move forecasting, and tax prep from one related system.
Did you get pleasure from this text?