With media megamergers, acquisitions and spin-offs left and proper, the media panorama is altering at a tempo that’s troublesome to maintain up with.
Right here’s a recap: Earlier this week, Comcast shared plans to spin off NBCUniversal and Sky right into a publicly traded firm. The information follows Sky saying plans to accumulate the media and leisure division of the European broadcaster ITV. However Comcast already separated lots of its cable belongings into a brand new firm referred to as Versant Media earlier this 12 months.
In the meantime, the opposite media and leisure gamers are getting greater by consuming one another. Paramount Skydance is about to soak up Warner Bros. Discovery, whereas Fox prepares to gobble up Roku. Walmart desires to be a media firm, too: It purchased the self-serve platform Vibe.co final week to bolster TV advert gross sales after shopping for good TV maker Vizio in 2024.
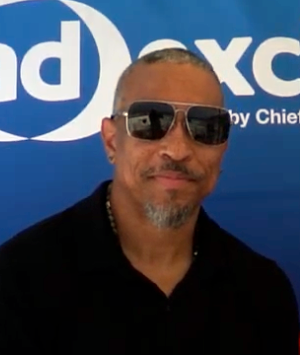
Behind all this transformation is a unanimous need to capitalize on the speedy rise of on-demand streaming, in response to Scott Schiller, adjunct professor of the leisure, media and expertise program on the NYU Stern College of Enterprise and principal at S350 Media Advisors. Schiller is a media and advert gross sales vet who labored at MTV, Sony, Disney, AOL and Comcast. He was on Comcast’s advertising workforce when the broadband large purchased a majority stake in NBCUniversal in 2011.
Fifteen years later, Schiller is reminiscing on what number of occasions he has seen firms consolidate and break up (typically repeatedly), because the trade scrambles to react to altering market expectations. However will Comcast’s new construction assist advertisers discover and have interaction their audiences as the remainder of the trade consolidates?
That query stays unanswered, however possible not for lengthy.
AdExchanger spoke with Schiller about what the altering media panorama means for customers, advertisers and the way forward for video advert shopping for.
AdExchanger: What do you make of Comcast’s resolution to spin off NBCUniversal amid all of the media mergers and acquisitions?
SCOTT SCHILLER: Media offers equivalent to spin-offs and mergers are monetary selections. In Comcast’s case, it’s separating its belongings to create two new firms that may extract worth from {the marketplace} in numerous methods.
Traders must see outcomes and sustainable monetary development, which drives media firms’ selections to restructure themselves. However offers like Comcast’s don’t at all times end in tangible advantages for the customers.
Then, what concerning the latest wave of media consolidation? How would possibly M&A have an effect on advertisers and customers?
Mergers and acquisitions [such as Paramount-WBD and Fox-Roku] are additionally monetary performs. M&A clearly ends in cost-cutting and efficiencies by way of consolidation. However, oftentimes, these advantages don’t at all times trickle right down to the buyer.
The pending Paramount-WBD deal may be riskier from the lens of shopper affect as a result of extra media entities will reside beneath one roof. That consolidation may affect shopper pricing along with content material manufacturing. For instance, if Paramount folds WBD’s streaming belongings into its personal, would that drive down prices for Paramount+ subscribers? Or would it not finally trigger value hikes on account of much less competitors and better advertiser demand for a smaller focus of stock? It’s too quickly to say, however I at all times suppose it’s higher to offer customers extra alternative, not much less.
Media consolidation doesn’t essentially end in higher content material or larger funding in programming. Particularly for the reason that definition of premium content material is evolving. Traditionally, the time period premium used to discuss with long-form, professionally produced content material developed for the large display screen on the wall. However these days, the essence of premium facilities on the content material that buyers really get pleasure from. If some individuals get pleasure from watching cat movies, then these movies are premium to that shopper.
Talking of cat movies, the place does YouTube match into this evolving media panorama?
YouTube is completely different in that it appeals to a number of sorts of constituencies: it’s a streaming platform with reside TV programming, on-demand video and creator-made content material. YouTube is sort of a buffet, which is complicated for an trade that’s used to purchasing media à la carte. However YouTube additionally appeals to media patrons by promising the info and metrics entrepreneurs search for to show their campaigns carried out.
[Editor’s note: Whether or not YouTube actually coughs up that data is a different story.]
Now that we lined the media panorama, what are advertisers making of those modifications?
When consolidation occurs, there’s usually a tug-of-war over stock pricing. Media firms count on consolidation to drive substantial will increase in income whereas businesses count on higher offers from shopping for a number of swimming pools of provide in bulk from the identical supply.
Pricing is one instance of an space the place M&A offers don’t at all times ship on the guarantees they got down to obtain for the ecosystem to start with. These offers are a monetary transaction that profit management and traders at a second in time.
That rationale might clarify why consolidation doesn’t solely exist amongst media and leisure firms. We’re seeing consolidation change the company panorama, too, notably with all of the AI improvements and developments meant to maximise media worth.
Maximizing advert efficiency is the principle precedence for patrons. How are you seeing this race to the underside have an effect on measurement?
Entrepreneurs are traditionally danger averse and so they need to use methods that they know work. With extra expertise and knowledge obtainable, there’s extra temptation to measure the whole lot. In actuality, efficiency means one thing completely different to each marketer, and it is rather troublesome to align particular person campaigns with particular efficiency metrics equivalent to in-store gross sales.
That temptation explains why each startup positions themselves with claims that they’ve the right measurement and attribution options. However I’m unsure that the trade is searching for the right approach to measure their media. They’re searching for a constant approach to measure.
What do you suppose? Have any suggestions or scorching takes? Let me know your ideas. Hit me up at alyssa@adexchanger.com.